Colorado Hail Damage Roof Insurance Claim Guide: How The Process Works
Quick answer: A hail damage roof insurance claim usually starts with documenting damage, scheduling an inspection, and opening a claim with your carrier. The challenge is that many first insurance estimates miss code items, pricing updates, or damage to siding, windows, gutters, trim, and other exterior components.
After a major hail storm, homeowners are often left trying to figure out what damage exists, what their insurance company should cover, and whether the first claim estimate is actually enough to restore the property correctly. This resource guide explains how a hail damage roof insurance claim works, where insurance estimates commonly fall short, and why a second opinion can matter.
Updated March 2026 • Insurance claim resource guide by Northern Lights Exteriors
How A Hail Damage Roof Insurance Claim Usually Works
When a hail storm or wind storm damages a home, the insurance claim process often moves quickly. The problem is that homeowners are expected to make important decisions while also dealing with temporary repairs, daily life, and time pressure.
In a typical hail damage roof insurance claim, the process looks like this:
- Document visible damage to the roof, siding, windows, gutters, trim, screens, and exterior components.
- Protect active leaks or exposed areas with temporary measures if needed.
- Have the property inspected for full exterior storm damage.
- Open a claim with the insurance company.
- Meet with the insurance adjuster during the site visit.
- Review the estimate carefully before assuming it includes everything needed.
- Complete repairs only after the full scope is understood.
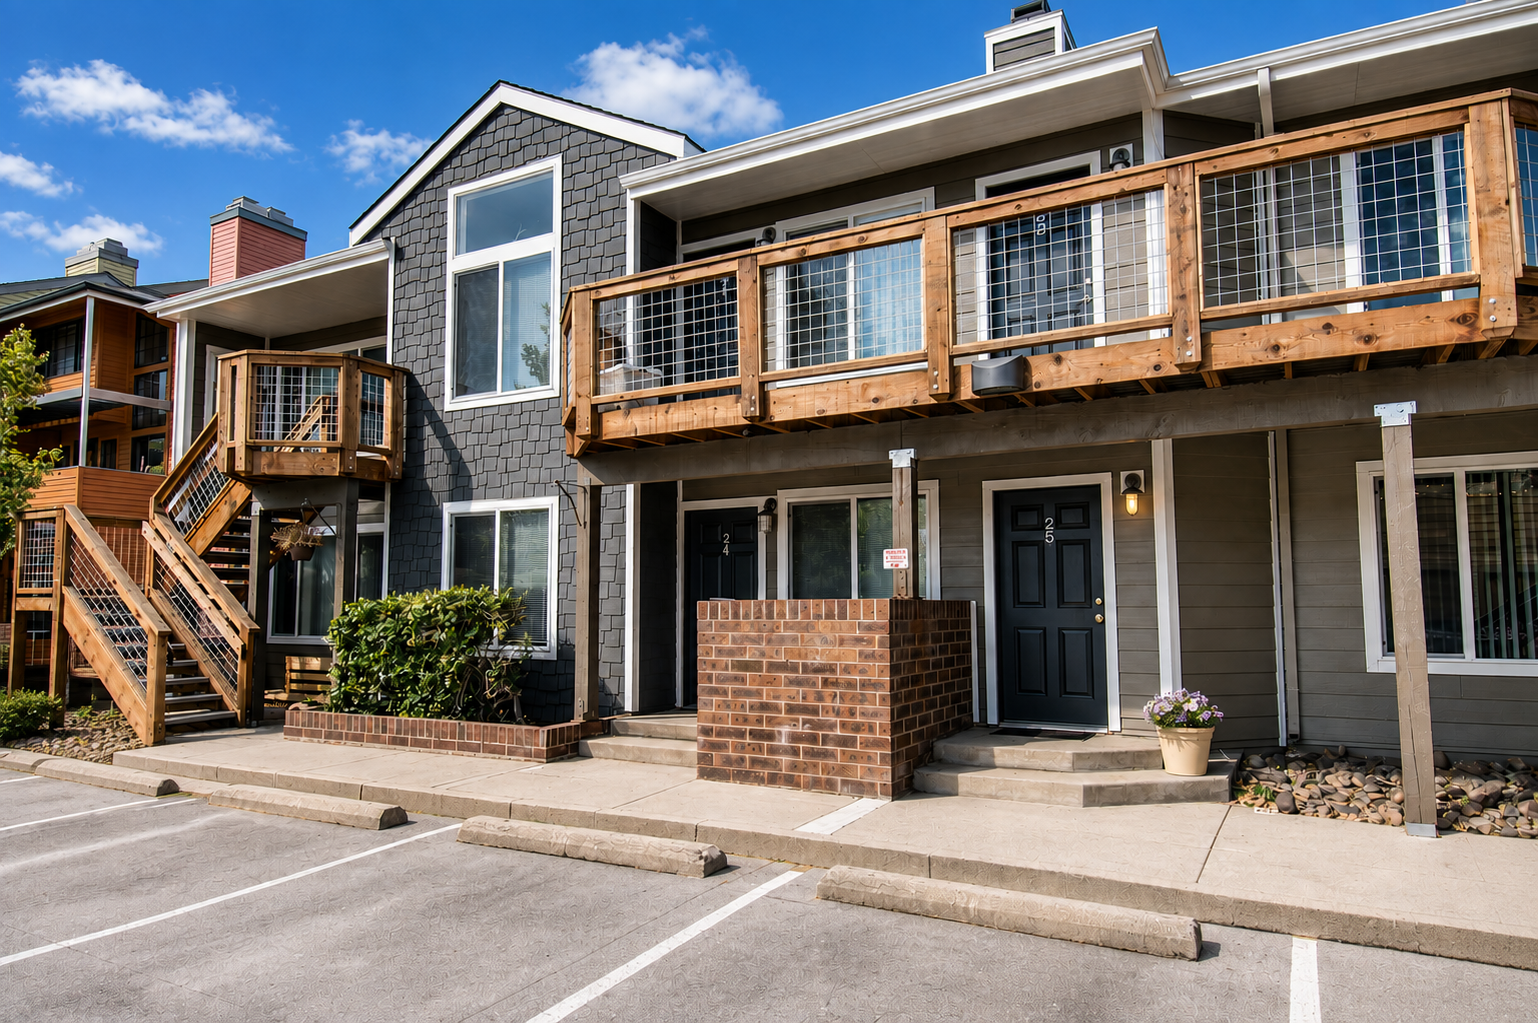
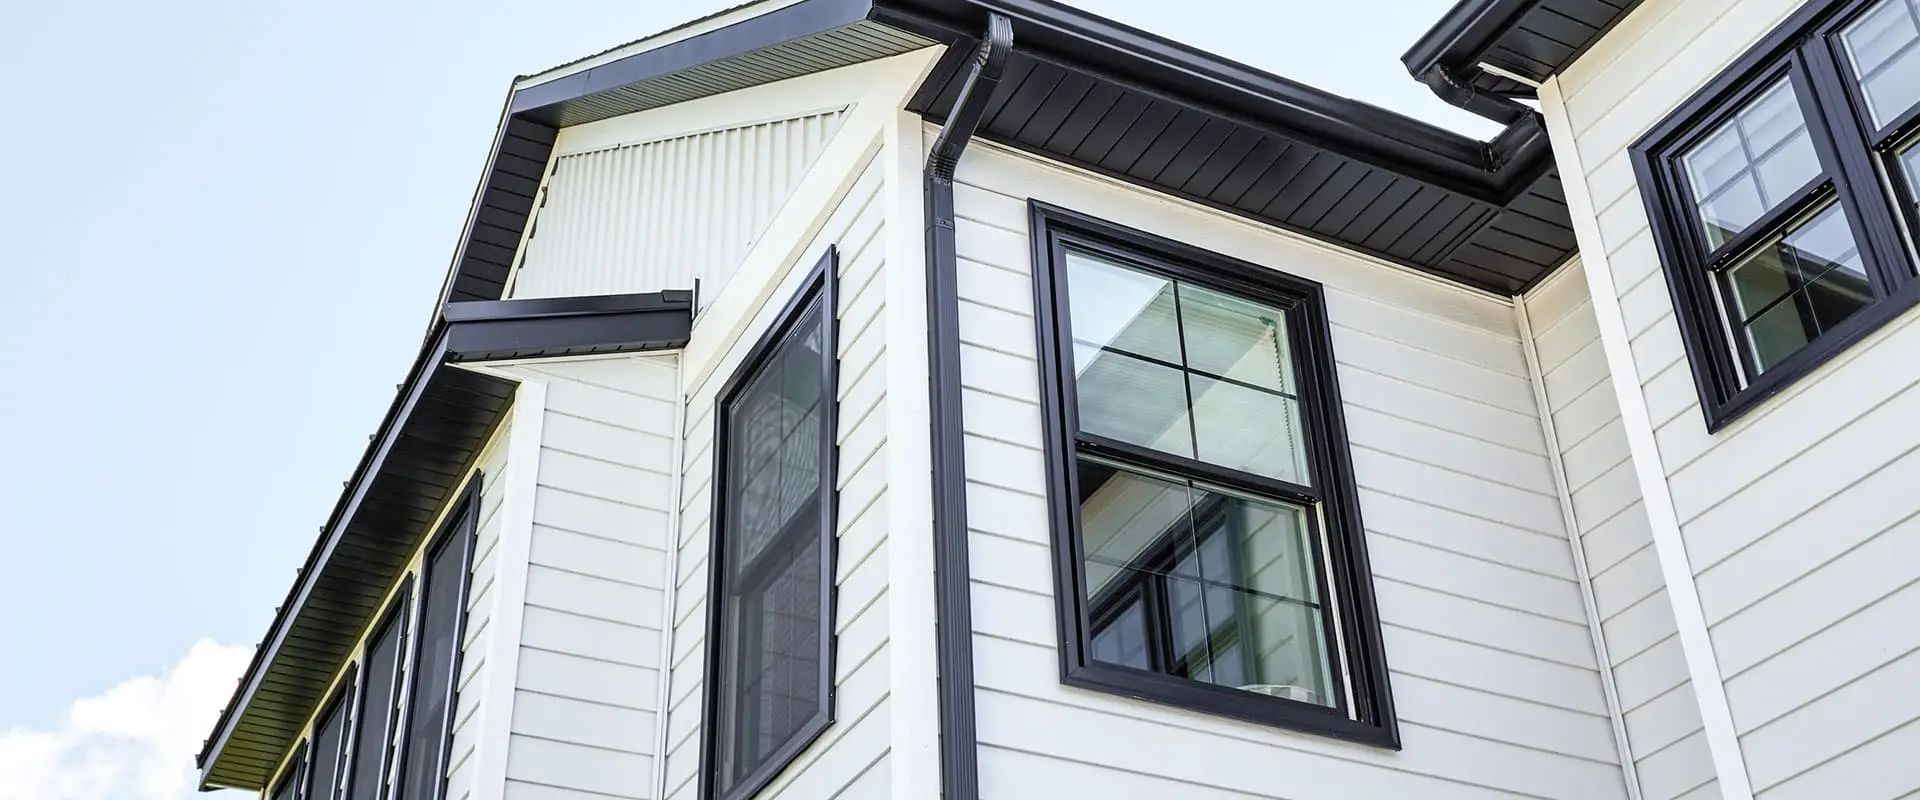
Many homeowners assume the claim is mostly about the roof. In reality, hail frequently damages siding, windows, gutters, trim, paint, and other exterior surfaces at the same time.
Where Hail Damage Insurance Claims Commonly Go Wrong
Insurance estimates are not always wrong, but they are not always complete either. After large Colorado storm events, adjusters are often handling a heavy volume of claims in a short period of time. In our experience, the bigger the storm, the more opportunity for misses….as out of state adjustors are often brought in to handle the claim load.
What homeowners often assume
- The first estimate must be the full amount owed
- The roof is the only damaged part of the property
- If the adjuster seemed confident, the scope must be complete
- Low contractor bids always mean savings
What often happens in reality
- Missing scope items are discovered later
- Code-related requirements were not included
- Pricing may not reflect actual local market conditions
- Damage to windows, siding, gutters, trim, or paint was missed
Key takeaway: A hail damage roof insurance claim should be reviewed as a full exterior restoration issue, not just a roofing line item. The property owner has the right to pick their contractor, and that contractor should have the full scope of work approved BEFORE work starts.
Does A Hail Damage Claim Raise Insurance Rates?
This is one of the most common questions homeowners ask after a storm: does hail damage claim raise insurance rates?
In general, hail and wind events are typically treated differently than at-fault auto claims because they are weather-related losses, not accidents caused by the homeowner. However, insurance pricing decisions can vary by carrier, market conditions, claim history, and broader storm activity in a region.
The safer takeaway is this: homeowners should not let fear or pressure keep them from properly documenting legitimate storm damage. The more important first step is to determine whether real damage exists and whether the estimate fully reflects what is needed to restore the property.
Why A Second Opinion Can Matter On A Roof Hail Damage Insurance Claim
Before major medical treatment, many people get a second opinion. Storm restoration deserves the same mindset.
In Colorado, code requirements, local municipality practices, material availability, and full exterior scope can all influence what a proper repair should include. That means a second opinion is often less about arguing and more about confirming whether the estimate actually reflects the real work required.
- Is the estimate using realistic local pricing?
- Were all damaged trades included?
- Were municipal code requirements addressed?
- Was matching of discontinued materials considered?
- Was window, siding, gutter, or trim damage missed?
For homeowners, the goal is simple: make sure the property is restored correctly, not partially.
What To Watch Out For During The Claim Process
- Do not feel pressured to sign paperwork on the spot.
- Do not assume the first estimate is final.
- Do not hand over insurance checks to a contractor before work starts.
- Do not choose a contractor based only on the lowest price.
- Do not ignore permits, code requirements, or city inspections.
After large storms, door-knocking contractors often focus on the easiest and fastest roof replacements. Homeowners are then left coordinating the harder trades on their own. That is one reason full exterior storm restoration can be a better long-term approach.
Related resource: read the Colorado hail damage resource guide.
Colorado Insurance Claim Case Studies
These examples show how claim outcomes can change when the full exterior scope is reviewed carefully.
Evans, Colorado
Case study: siding scope and matching issues
Initial situation: The insurance estimate called for limited siding replacement and reuse of removed siding on another elevation.
What we found: The siding was about 20 years old and no longer available, which would have created a visible mismatch across the home.
Result: The insurance company agreed the original approach was not in the homeowner’s best interest and paid to replace the siding for the entire house.
Windsor, Colorado
Case study: roof, siding, and window damage missed in first estimate
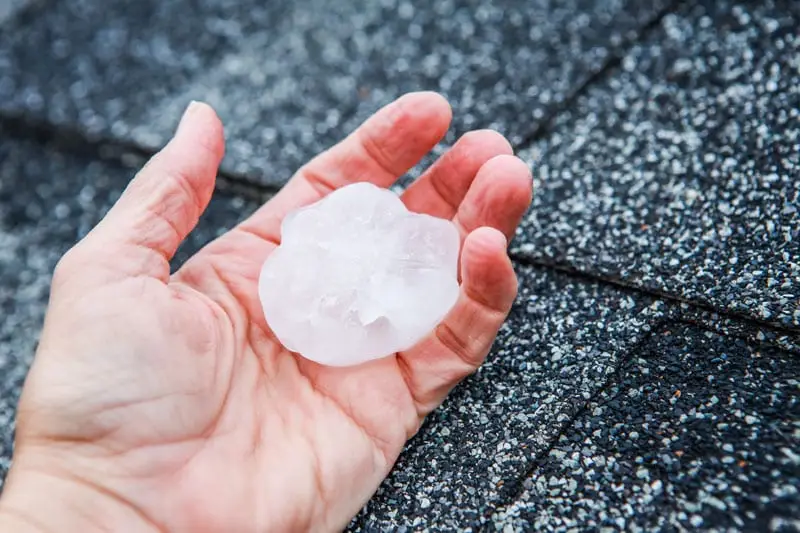
Initial situation: The homeowner had an offer that included one window, a sliding glass door, and a few small roof items.
What we found: Additional windows were damaged, siding on two sides was affected, and the roof needed replacement.
Result: After a fuller inspection and follow-up with the carrier, the claim was rewritten to reflect the broader storm damage scope.
Dollars-And-Cents Claim Examples
Below are additional examples of claim revisions after closer review of damage, code-related items, pricing, and full exterior scope.
Longmont, CO
Original estimate: $17,000
Final claim: $25,767.92
Additional amount: $8,767.92
Increase: 51.6%
Lafayette, CO
Original estimate: $22,197
Final claim: $33,299
Additional amount: $11,102.00
Increase: 50.0%
Boulder, CO
Original estimate: $74,852
Final claim: $241,829.01
Additional amount: $166,977.01
Increase: 223.1%
Brighton, CO
Original estimate: $12,055.94
Final claim: $20,608.00
Additional amount: $8,552.06
Increase: 70.9%
Frederick, CO
Original estimate: $5,794.00
Final claim: $14,719.00
Additional amount: $8,745.00
Increase: 146.4%
Louisville, CO
Original estimate: $15,615.00
Final claim: $56,788.64
Additional amount: $41,173.64
Increase: 263.7%
Important: These examples are case-specific and do not guarantee the same outcome on every hail damage roof insurance claim. Claim results depend on the actual storm damage, policy terms, municipality requirements, and the quality of the initial estimate.
Frequently Asked Questions About Roof Hail Insurance Claims
What is a hail damage roof insurance claim?
A hail damage roof insurance claim is a property insurance claim filed after hail damages roofing materials or other exterior parts of a home.
Should I trust the first insurance estimate?
The first estimate may be accurate, but homeowners should still review it carefully and consider a second opinion when damage appears broader than the written scope.
Does hail damage claim raise insurance rates?
Weather-related claims are generally treated differently than at-fault accident claims, but insurance pricing can still vary by carrier, market, and claim history. The most important first step is confirming whether legitimate storm damage exists.
Can hail damage affect more than the roof?
Yes. Hail can damage siding, windows, gutters, screens, trim, paint, and other exterior components during the same storm event.
Why do some claims get rewritten?
Claims may be revised when additional damage is documented, local code requirements are identified, market pricing is corrected, or missing scope items are added.
Should I use a roof-only contractor for a hail claim?
Many homeowners are better served by a contractor who understands the full exterior scope, especially when storm damage affects more than just roofing materials.
Need A Second Opinion On A Colorado Hail Insurance Claim?
If you have a hail damage roof insurance claim and want a more complete review of the property, a full exterior inspection can help identify missed items before repairs begin.
Northern Lights Exteriors works with Colorado homeowners on roofing, siding, windows, gutters, and storm restoration projects, with a focus on understanding the full repair scope. For a deeper look at how the scope gets completed — underscoped items, permits at actual cost, tear-off discoveries, and the window and door pricing gap — see how roof claim supplements work in Colorado.